Merchants on the Edge: How Small Businesses Are Rewiring Their Pricing After the Surcharge Ban
The Morning After the Ban
Bakery owner Dylan McQueen did the maths long before the law changed. Last financial year, his Mount Gambier business paid $5,785 in card fees, even though cash made up only 16 per cent of transactions. Like thousands of small operators, he never surcharged—partly out of principle, partly because he suspected customers would punish him for it. When the national ban took effect on 1 October 2026, McQueen’s position shifted from philosophical to operational: the fee is still there, but the ability to pass it on has vanished.
The Absorb-or-Adjust Dilemma
For merchants, the surcharge ban is not a cost-cutting measure. It is a cost-reallocation mandate. The RBA did reduce interchange fee caps—dropping the maximum consumer credit card interchange rate from 0.8% to 0.3%—and estimated that businesses would save around A$910 million annually in card payment costs. That relief is meaningful, but it does not arrive evenly. Small merchants often pay higher effective rates than large chains, and the savings timeline depends on acquirers passing through the cuts.
The result is a patchwork of responses. Some businesses have swallowed the fee and trimmed margins. Others have raised menu prices, sometimes by more than the fee itself. A nursery owner interviewed by the ABC described merchant fees as “tens of thousands” in annual costs and said he would still need to lift prices despite recent bank fee reductions. The surcharge has been removed from the receipt, but the cost has not disappeared from the P&L.
Cash as a Pressure Valve
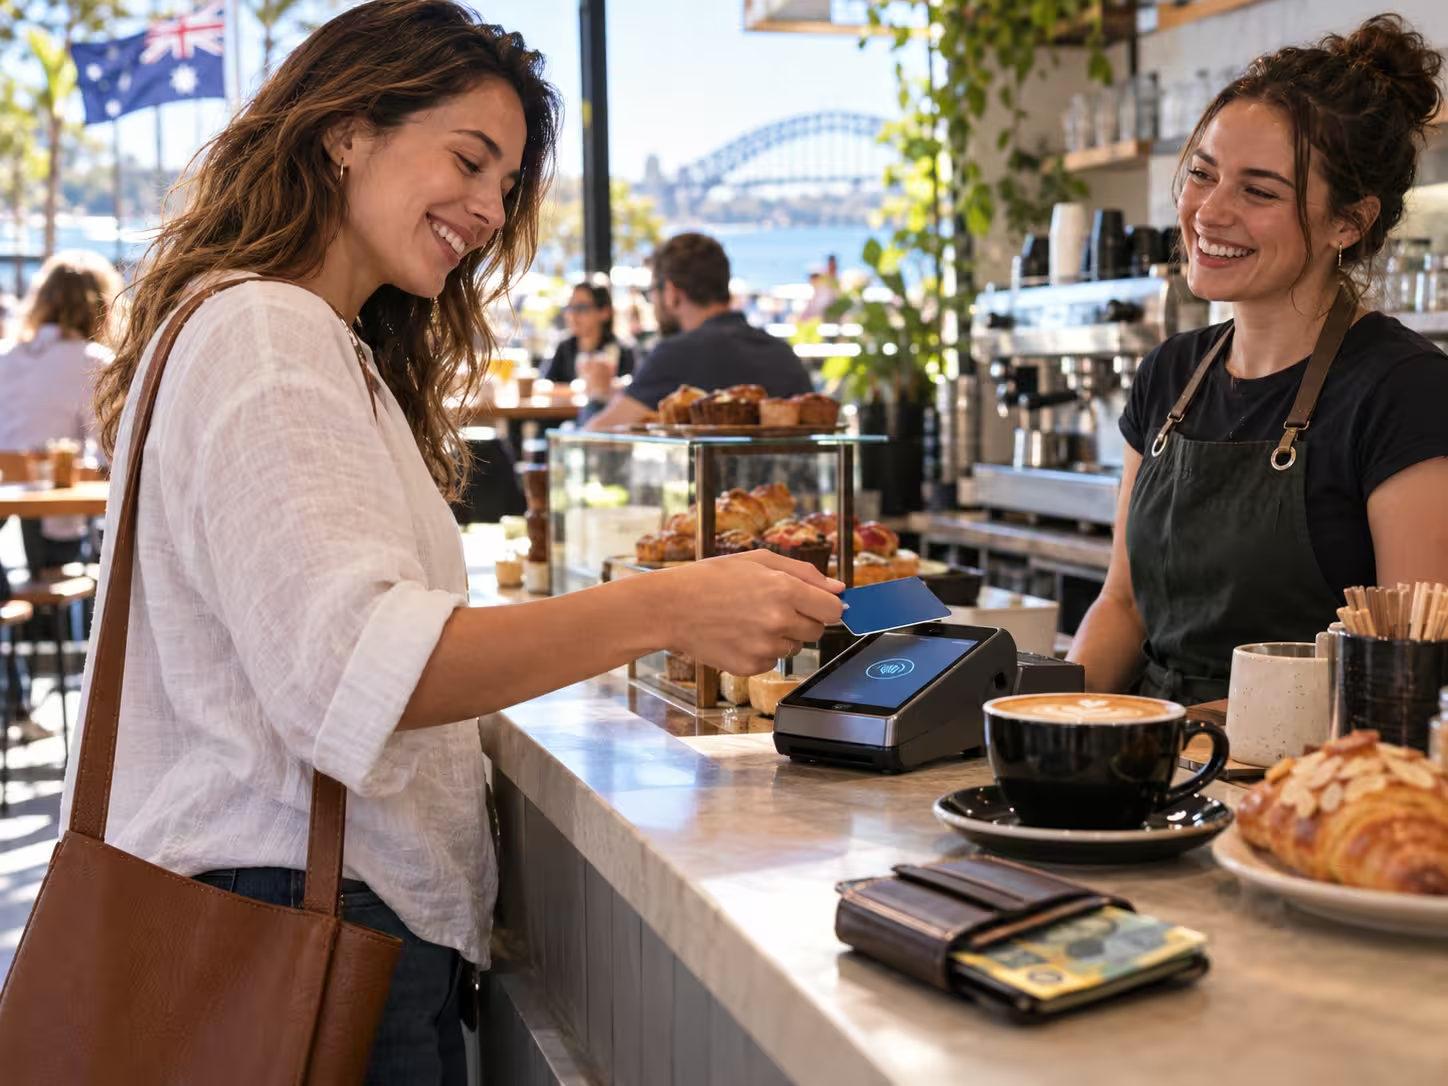
The most visible merchant strategy is the cash discount, a legal workaround that the ACCC has explicitly endorsed. By encouraging customers to pay with notes, businesses avoid card processing costs entirely and can offer a small incentive without violating the surcharge rules. One supermarket reported a 30 per cent jump in cash sales within a week of the changes, suggesting that consumer behaviour is more malleable than decades of card-first marketing implied. For merchants, cash is not nostalgia—it is a margin defence mechanism.
The Compliance Trap
There is also a regulatory trapdoor. Businesses cannot simply rename a card surcharge as an “admin fee” or “processing fee” and carry on as before. The ACCC has warned that any charge effectively triggered by card payment remains prohibited, and misleading pricing information can attract enforcement action. For operators already stretched by rent, wages, and input costs, the compliance burden is another line item on an increasingly crowded ledger.
The Road Ahead for the High Street
The surcharge ban has forced small businesses to confront a question they had long deferred: what does it actually cost to accept money in 2026? The answer is no longer hidden at the bottom of a receipt. It is baked into the price of a flat white, the cost of a seedling, and the viability of the corner store. The merchants who thrive will be those who treat payment costs as a strategic input rather than an afterthought—and who communicate pricing changes with the transparency the new regime demands.